rapid! Pay

Screenshots
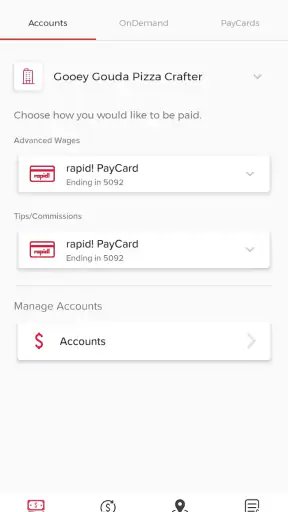
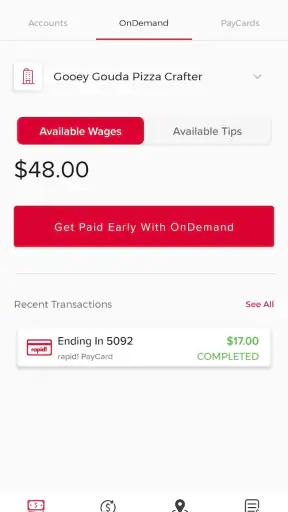
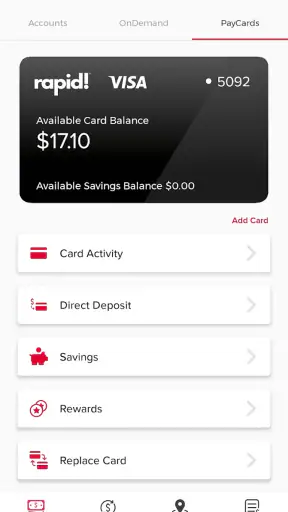
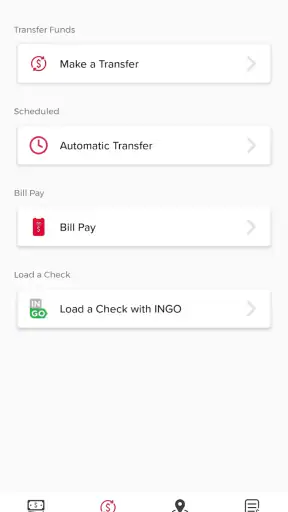
Details
- Rating
- 13.77K reviews
- Version
- 1.0.116
- Developer
- Green Dot
Analysis by Norviv
Managing a rapid! account from a phone is the main reason to look at rapid! Pay. It is a free finance app from Green Dot, built for people who already use the rapid! card service and want account access without relying on a desktop browser. I found its purpose fairly clear: it puts everyday cardholder tasks in a mobile setting, rather than trying to be a general banking replacement for everyone.
The app’s average rating is 4.3 from around 78,000 ratings, and it has passed one million installs. Those figures suggest that it has reached a substantial audience, although popularity alone does not tell me whether it will suit your particular financial routine. My view is more practical: rapid! Pay can be useful when your card activity is already tied to rapid!, but it is a less convincing choice if you are looking for a complete money-management app with broad banking tools.
What rapid! Pay is really for
The developer, Green Dot, positions rapid! Pay as a cardholder mobile app rather than a budgeting suite or an investment platform. That distinction matters. When I approach it with the expectation of checking and handling a rapid! account from my phone, the app makes sense. When I compare it with a full-service bank app, the narrower purpose becomes much more obvious.
Its store summary focuses on registering new rapid! users, while the short description presents it as a payment-focused tool. In everyday terms, I would think of it as a companion for rapid! card use: a place to begin or manage the relationship from a mobile device, depending on your situation. It is not the kind of app I would choose simply because I want a universal wallet for several unrelated financial accounts.
The age classification is Everyone, which makes the presentation approachable for a broad audience. It was released on October 30, 2020, and the current version is 1.0.116. Compatibility begins with Android 7.0, so people using older phones should check their device before planning around it. For a modern Android user, that requirement is unlikely to be the main decision point, but it is still worth noticing if this is an older spare handset used for financial tasks.
Cost: free access, not a promise about every financial charge
Downloading rapid! Pay costs nothing. That is the clearest value point, especially for someone who only needs mobile access to an existing rapid! card account. I can install a free app, test whether its account workflow fits my needs, and remove it without paying for the software itself.
Still, “free app” should not be confused with “every service connected to it is free.” The app’s price tells me what I pay to obtain the application, not what every card-related action or account service might cost. I would read the relevant rapid! terms carefully before relying on it for a particular transaction. That is a more responsible way to judge the cost than assuming the absence of an app charge covers the entire financial product.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
This distinction also affects comparisons. A traditional bank app may be free to download too, while the underlying account has its own conditions. A budgeting app can also be free at the installation stage but limit useful tools behind another arrangement. rapid! Pay’s advantage is therefore straightforward mobile access at no download price, not a guaranteed saving on all money movement.
How the mobile experience fits a normal day
Picture a worker who receives money through a rapid! card and is away from a computer when they want to check their account or manage card-related activity. Opening a dedicated cardholder app is more convenient than waiting until they can reach a browser. That is the strongest everyday scenario I see for rapid! Pay: short, account-specific tasks handled from the same device used for other daily payments.
I also see value for someone registering a new rapid! card. Instead of treating registration as a one-time desktop chore, the app makes the mobile device part of the starting process. I would keep the card and personal account details close at hand, use a private connection, and avoid rushing through identity or account fields. A small mistake during setup can create more frustration than the app itself.
Another sensible workflow is to separate rapid! Pay from general spending apps. I would use this app for rapid!-specific account attention, then use a separate budgeting tool if I wanted categories, long-term planning, or a combined view of several accounts. That division keeps expectations realistic and may make the phone less cluttered than trying to force one app to do everything.
The practical strengths I noticed
The first strength is focus. Because rapid! Pay is aimed at rapid! cardholders, I do not expect to navigate a large collection of unrelated financial products before reaching the account area I actually need. For an existing user, that narrower design can feel more direct than a broad banking application filled with features that have nothing to do with a prepaid or payroll-linked card routine.
The second is accessibility of timing. A mobile card app is useful precisely when a computer is not nearby. That can matter before a purchase, while checking whether an expected payment is available, or when beginning registration during a work break. The convenience is not dramatic, but financial tasks often benefit from being available at the moment a question comes up.
The third is the low-risk way to evaluate the software. Since the app is free, I can see whether its navigation and account workflow suit me without committing money to the download. That does not remove the need to understand the card’s terms, but it does make the software itself easy to try.
There is also a less obvious benefit in keeping card access separate from a primary bank account. Some people prefer a dedicated app for a dedicated card because it reduces the chance of confusing balances, transfers, or payment sources. That is not a reason to abandon a bank’s security practices, but it can make a simple card routine easier to follow.
Where the trade-offs become important
The biggest limitation is scope. I would not install rapid! Pay expecting the full planning experience of a major bank or a specialist budgeting service. If your goal is to see checking, savings, credit cards, investments, bills, and household categories in one dashboard, a broader financial platform is probably the better fit.
The app’s usefulness is also tied to being a rapid! cardholder. That sounds obvious, but it is the most important filter. If you do not use rapid!, the registration-oriented purpose gives you little reason to keep the app. Even if you are considering the card, I would first decide whether the underlying account matches your needs rather than choosing the financial product because its mobile app is free.
Mobile convenience can introduce its own friction. A phone may be lost, shared, low on storage, or protected by weak device security. For a finance app, I would use a strong screen lock, keep the operating system supported, and avoid signing in on someone else’s device. These are not special rapid! Pay features; they are sensible habits when an app gives access to card information.
I would also avoid treating an app screen as a substitute for reviewing transaction details. A quick glance is useful, but a careful check still matters when something looks unfamiliar. The best workflow is to use rapid! Pay for timely account awareness and then pause over important activity instead of approving or ignoring it automatically.
How it compares with usual alternatives
Compared with a desktop website, rapid! Pay wins on immediacy. I can reach a card-focused experience from a phone without opening a full browser session. The website may feel more comfortable for long forms or detailed reading, while the app is better suited to short checks and mobile registration.
Compared with a mainstream bank app, rapid! Pay is more specialized. A bank application usually makes more sense when my financial life is centered on a checking account, recurring payments, transfers, and several products from the same institution. rapid! Pay makes more sense when the rapid! card itself is the center of the task.
Compared with a budgeting app, the difference is even clearer. Budgeting software is designed around spending analysis and planning, while rapid! Pay is connected to cardholder access. I would not expect it to replace a budget, and I would not blame it for lacking the wide account aggregation that makes a budgeting tool useful. They solve different problems.
Compared with using no app at all, the benefit is convenience rather than a new financial strategy. If you rarely check your rapid! account and are comfortable with another access method, rapid! Pay may not change your routine much. If you need mobile access at ordinary moments during the day, the dedicated app has a stronger case.
Who is most likely to get real value
I would recommend trying rapid! Pay to an active rapid! cardholder who wants a direct phone-based way to register or manage the card relationship. It is particularly sensible for people whose card is part of their regular payment routine and who do not want to depend on a computer for every account question.
It also suits someone who values a focused tool over a large financial dashboard. If seeing only rapid!-related information feels cleaner than mixing it with several bank accounts, the app’s narrower role can be an advantage. The free download makes that experiment easy, provided the underlying card service is already appropriate for you.
I would be more cautious about recommending it to a person choosing their first all-purpose financial app. That user may need bill organization, detailed spending categories, multiple-account visibility, or broader banking support. In that case, rapid! Pay could be one small part of the setup, but it should not be mistaken for the whole solution.
It is also not my first suggestion for someone using an unsupported older Android device. The minimum operating system is Android 7.0, and financial access is not something I would force onto a phone that can no longer receive dependable security maintenance. A supported device with a lock screen is a better starting point than squeezing the app onto aging hardware.
Small habits that make the app more useful
Before registering, I would prepare the card and account information, then complete the process in one quiet session rather than between errands. That reduces typing errors and makes it easier to notice whether each detail has been entered correctly. For a finance app, a few extra seconds during setup are worth more than speed.
I would also decide what rapid! Pay is responsible for in my personal routine. For example, I might use it for rapid! account access and card checks, a separate app for monthly budgeting, and my main bank app for unrelated accounts. Defining those boundaries prevents the common mistake of judging a focused card app against features it was never meant to provide.
Finally, I would keep notifications and device security under regular review. I would not share the phone casually, and I would sign out or remove access if the device changed hands. These steps are especially important when the app is convenient enough to become part of everyday spending habits.
My verdict on downloading rapid! Pay
rapid! Pay is worth trying when you already use rapid! and want free mobile access to its cardholder experience. Its value comes from focus, convenience, and a straightforward reason to exist: bringing rapid!-specific account tasks to an Android phone. The rating of 4.3 and audience of more than a million installs show that many people have found a reason to use it, but I would still judge it by my own card routine rather than by popularity.
I would skip it if I need a complete personal-finance command center, if I do not use rapid!, or if I am selecting a financial product solely because the companion app has no download price. In those situations, a full bank app, budgeting service, or another card provider may serve the larger need better.
For the right user, though, the decision is simple. Install it on a supported, secured Android phone, use it for rapid!-related access, and keep your expectations tied to that purpose. My final opinion is positive but deliberately limited: rapid! Pay is a useful companion for rapid! cardholders, not a replacement for every other financial tool.
Frequently Asked Questions
01What is rapid! Pay and what can I use it for?
rapid! Pay is a mobile payment app designed to help users manage everyday purchases and transactions from their smartphones. Depending on the account and region, it may support payments at participating merchants, access to available funds, transaction tracking, and account-related services. Before downloading, check whether rapid! Pay is officially supported in your country and whether your employer, card issuer, or participating retailer is required for full access.
02Is rapid! Pay safe to use for payments and personal information?
rapid! Pay typically relies on account authentication and security controls to protect payment activity and personal data. However, no financial app is completely risk-free. Use the official version from Google Play or the App Store, create a strong password, enable device security, and avoid sharing verification codes. Review the app’s privacy policy carefully so you understand what information may be collected, stored, or shared.
03Do I need a specific account, card, or employer to use rapid! Pay?
Access requirements can vary depending on the version of rapid! Pay and the services offered in your location. Some users may need an eligible rapid! account, payment card, payroll connection, employer relationship, or invitation before they can use all features. Installing the app alone may not be enough. Confirm the eligibility rules, supported cards, and registration requirements before expecting to make payments.
04Are there fees, spending limits, or transaction restrictions in rapid! Pay?
The cost of using rapid! Pay depends on the transaction type, account agreement, and local service terms. Some features may be free, while certain transfers, withdrawals, card services, or out-of-network transactions could involve charges. There may also be daily or monthly limits, merchant restrictions, and verification requirements. Read the current fee schedule and user agreement inside the app before relying on it for regular payments.
05What should I do if a payment fails or my rapid! Pay account is locked?
If a payment is declined, first check your internet connection, account balance, card status, merchant compatibility, and any spending limits. Avoid repeatedly entering incorrect login details, as this may trigger a temporary lock. Use the in-app help or official rapid! Pay support channels for assistance, and keep transaction references or screenshots available. Never contact unofficial support accounts or disclose your password, PIN, or security codes.


